
Introduction If you run any food business in India, you must obtain FSSAI Registration or License. The government has made this mandatory to ensure food safety, hygiene, and consumer protection. Today, FSSAI works as a strict and technology-driven regulator. It monitors food businesses through digital systems, inspections, and structured compliance rules. Therefore, every Food Business […]
Companies Act
SA 450 – Evaluation of Misstatements Identified During the Audit
Introduction During the course of an audit, the auditor may identify errors, omissions, or incorrect disclosures in the financial statements. These are known as misstatements. SA 450 provides a clear framework for dealing with such misstatements in a systematic and professional manner. This Standard ensures that the auditor evaluates every identified misstatement properly, communicates it […]
Section 194J – TDS on Professional and Technical Services
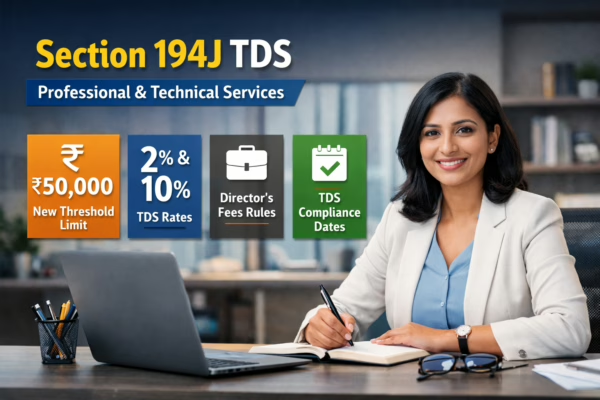
Introduction Section 194J of the Income Tax Act governs Tax Deducted at Source (TDS) on payments made for professional and technical services. Whenever a business pays fees to doctors, lawyers, engineers, consultants, or technical experts, it must deduct TDS before making the payment. As of February 2026, the provisions amended by the Finance Act 2025 […]
SA 402 – Audit Considerations Relating to an Entity Using a Service Organisation
Introduction SA 402 applies when an entity uses a service organisation to perform functions that are relevant to financial reporting. These services may include payroll processing, cloud accounting, IT infrastructure, data management, or transaction processing. This Standard explains how the auditor applies SA 315 (Identifying and Assessing the Risks of Material Misstatement) and SA 330 […]
SA 330 – The Auditor’s Responses to Assessed Risks
Introduction SA 330 requires the auditor to respond appropriately to the risks of material misstatement identified during the audit. After assessing risks, the auditor must design and perform audit procedures that directly address those risks and obtain sufficient appropriate audit evidence. Objective of SA 330 The auditor aims to obtain sufficient and appropriate audit evidence […]