
Introduction
Input Tax Credit (ITC) plays a pivotal role in the GST framework by ensuring that tax applies only to the actual value added at each stage of supply. In other words, it prevents the burden of tax from piling up and keeps the system fair and transparent. Moreover, ITC directly impacts cash flow, pricing, and overall compliance for every registered taxpayer. Therefore, understanding how ITC operates—and how to claim it correctly—is not optional but essential. This article breaks down Input Tax Credit in a practical, easy-to-follow, and up-to-date manner to help taxpayers stay compliant while maximizing legitimate tax benefits.
What Is Input Tax Credit (ITC)?
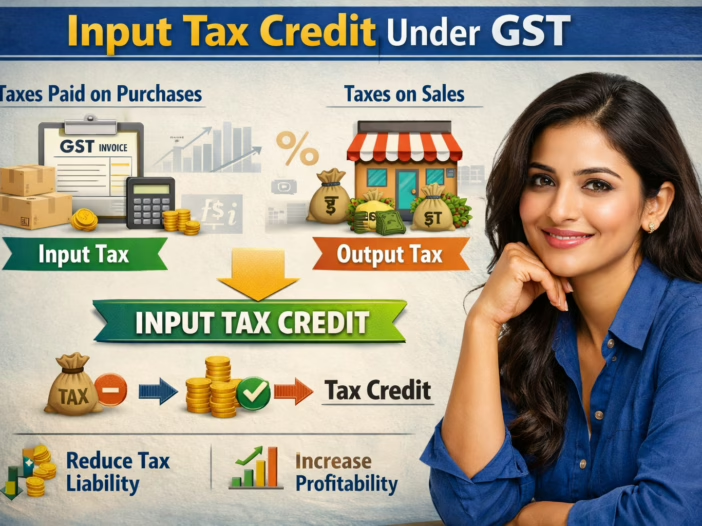
Input Tax Credit refers to the GST paid on purchases of goods or services used in the course or furtherance of business. A registered person can adjust this tax against the GST payable on outward supplies.
In simple terms, businesses pay GST on purchases and collect GST on sales. Through ITC, the tax paid on purchases is reduced from the tax payable on sales, and only the balance amount is paid to the Government.
Why ITC Is Important under GST
Firstly, ITC reduces the overall tax burden on businesses.
Secondly, it improves cash flow by lowering immediate tax outgo.
Moreover, it promotes transparency and compliance in the supply chain.
As a result, proper ITC management directly supports profitability and smooth GST compliance.
Conditions to Claim Input Tax Credit
To avail ITC, the following conditions must be fulfilled:
- A valid tax invoice or debit note must be available
- Goods or services must be actually received
- The supplier must have paid GST to the Government
- The recipient must have filed GSTR-3B
- The invoice must be reflected in GSTR-2B
If any of these conditions are not met, ITC may be denied or reversed.
Time Limit for Availing ITC
ITC must be claimed on or before:
- 30th November following the end of the relevant financial year, or
- The date of filing the annual return,
whichever is earlier.
Therefore, timely reconciliation is crucial to avoid permanent loss of eligible ITC.
Role of GSTR-2B in ITC
GSTR-2B is a static auto-generated statement that shows eligible and ineligible ITC for a particular month. Since it does not change after generation, it serves as the primary base for claiming ITC.
Hence, taxpayers should regularly reconcile:
- Purchase register
- GSTR-2B
- GSTR-3B
This practice helps avoid notices, reversals, and interest liability.
Eligible ITC and Blocked ITC
Eligible ITC
ITC is generally available on:
- Inputs used for business
- Input services
- Capital goods used in business
Blocked ITC
However, GST law restricts ITC on certain expenses such as:
- Motor vehicles for personal use
- Food and beverages (subject to exceptions)
- Club memberships and personal benefits
- Goods lost, stolen, destroyed, or given as gifts
Thus, expense review before claiming ITC is essential.
ITC Reversal Provisions
ITC must be reversed in cases where:
- Goods or services are used for non-business purposes
- Supplies relate to exempt outward supplies
- Payment is not made to the supplier within 180 days
- ITC is wrongly or excess claimed
Once conditions are satisfied again, eligible ITC can be re-availed.
Order of Utilisation of ITC
The utilisation of ITC must follow this order:
- IGST Credit → IGST → CGST → SGST
- CGST Credit → CGST → IGST
- SGST Credit → SGST → IGST
Cross-utilisation between CGST and SGST is not allowed.
Best Practices for ITC Compliance
- Reconcile ITC every month
- Track supplier GST compliance
- Avoid claiming ITC on blocked credits
- Maintain proper invoices and payment records
- Seek professional review for complex GST matters
These steps help minimize GST disputes and ensure smooth compliance.
Frequently Asked Questions (FAQs) –
- What is Input Tax Credit under GST?
Input Tax Credit means the GST paid on business-related purchases that can be adjusted against GST payable on sales.
- Can ITC be claimed without appearing in GSTR-2B?
No. ITC should be claimed only if the invoice is reflected in GSTR-2B.
- What is the time limit to claim ITC?
ITC must be claimed on or before 30th November following the end of the financial year or before filing the annual return, whichever is earlier.
- Is ITC available on capital goods?
Yes. ITC is available on capital goods used for business, provided depreciation is not claimed on the GST component.
- What happens if payment to the supplier is not made within 180 days?
ITC must be reversed with interest. However, it can be reclaimed once payment is made.
- Is ITC allowed on personal expenses?
No. ITC is not allowed on goods or services used for personal or non-business purposes.
- What expenses are blocked from ITC?
Expenses like food and beverages, club memberships, personal motor vehicles, and goods given as gifts are generally blocked.
- What is the correct order of ITC utilisation?
IGST credit must be utilised first, followed by CGST and SGST, as prescribed under GST law.
Conclusion
Input Tax Credit is a key GST benefit, but it demands strict and continuous compliance. By claiming ITC strictly as per GSTR-2B and within prescribed timelines, businesses protect their cash flow. Moreover, avoiding blocked credits reduces the risk of interest and penalties. Regular reconciliation further strengthens accuracy and transparency. Ultimately, disciplined ITC management ensures smooth, compliant, and dispute-free GST operations.